Your bank shows an electronic routing number and a wire routing number. The payment form has just one box labeled Routing number. Which goes there? First check whether you selected ACH or a wire, then use the bank details for that method. Here’s how to read the fields and resolve a mismatch before money moves.
What is an ACH routing number?
A U.S. routing number has nine digits. For ACH, it helps route an electronic payment to the correct financial institution. The separate account number tells the institution which customer account to credit or debit. An account name, account number and routing number each have a different job.
The American Bankers Association’s routing-number guide explains the system and its ACH and wire payment attributes. You may see ACH, electronic payments, direct deposit or ABA routing number in banking instructions. Read the payment-method label alongside the number.
Scroll across the table to see all columns.
| What you’re doing | Details to obtain |
|---|---|
| Receiving a payroll direct deposit | Your receiving account’s ACH routing and account numbers, using your employer’s verified setup process. |
| Authorizing a biller to pull an ACH payment | The ACH details of your funding account, plus your authorization for the debit. |
| Sending an ACH credit to someone else | The recipient’s verified receiving details for ACH. |
| Sending a domestic bank wire | The recipient’s bank-wire instructions, including the routing number designated for that wire. |
Where to find your ACH routing number
Open your bank’s app or type its official website address yourself. Select the exact checking or savings account, then look for Account details, Routing and account numbers, or Direct deposit. Choose the number labeled for ACH or electronic payments when the bank lists several options.
On many personal checks, the routing number is the nine-digit group at the bottom left. Account and check numbers also appear along the bottom, and layouts vary. If your check is old, your bank has merged, or the app shows a different number, ask the bank which ACH details to use.
A bank’s public lookup can help, but follow its selection instructions carefully. For example, Bank of America’s routing FAQ distinguishes electronic payments from wires and uses the state where the account was opened. Moving to another state alone is a poor reason to choose a new number from a search result.
A useful question for bank support: “For my checking account ending in [last four digits], which routing number should I use for an ACH debit? Is it also the number for incoming ACH credits?” Contact the bank through its app or the number on your card, and describe the payment you’re setting up.
Read the bank details: an annotated example
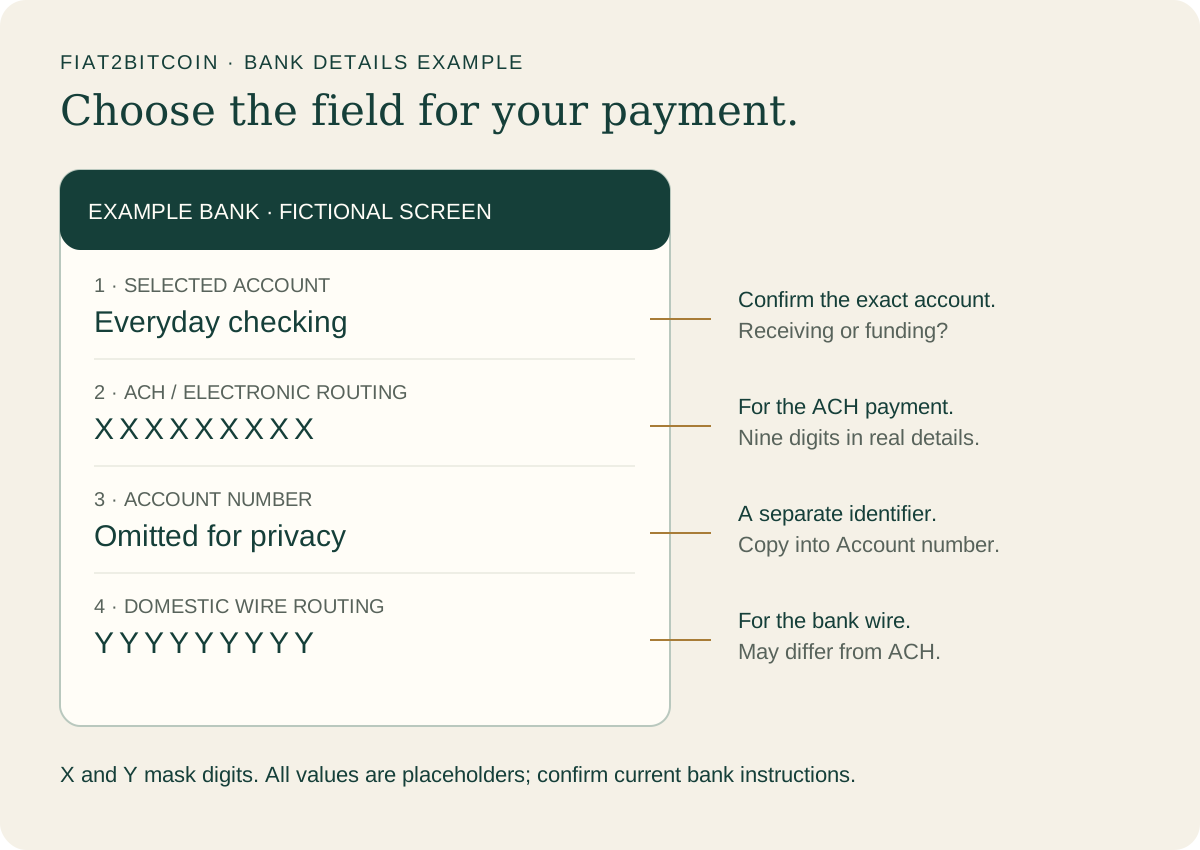
Imagine your account-details screen shows the fields listed here. The diagram uses a fictional bank and masked values. Each X or Y stands in for a digit; these letters are placeholders. Keep real account details out of screenshots you post publicly.
Scroll across the table to see all columns.
| Field | Masked example | How to use it |
|---|---|---|
| 1. Selected account | Everyday checking · account number omitted | Confirm this is the account you intend to receive into or authorize a debit from. |
| 2. ACH / electronic routing | XXXXXXXXX · nine masked digits | Copy the actual nine-digit number from your bank for the ACH payment. |
| 3. Account number | Omitted | Copy the complete account number into its separate field. Its length depends on the bank. |
| 4. Domestic wire routing | YYYYYYYYY · nine masked digits | Use the wire instructions for a wire. Ask the bank when the ACH and wire fields disagree. |
Copy numbers as written, including leading zeros. Review them after pasting. If a form rejects the number, confirm the country, payment method and selected account before editing anything. Ask the bank or payment service to resolve the error instead of shortening a number to make it fit.
Is an ACH routing number the same as a wire routing number?
Sometimes a bank uses the same routing number for both; sometimes it assigns different ones. Wells Fargo’s account-and-routing explainer describes how routing details can vary by payment type and account history. Your bank’s current instructions for the specific account and payment are the useful reference.
Both ACH and domestic wire instructions can contain a nine-digit ABA routing number. Choose the number labeled for the service you selected. For international transfers, follow the bank’s country- and currency-specific instructions; see our IBAN versus routing number guide for forms asking for an IBAN.
Scroll across the table to see all columns.
| Check | ACH payment | Domestic wire |
|---|---|---|
| Payment method | ACH credit or authorized ACH debit | Bank wire selected in the sending bank’s transfer service |
| Routing field | Number approved for ACH / electronic payments | Number specified in the receiving wire instructions |
| Other details | Account number, account type and requested account-holder details | Recipient details, account number and any additional bank instructions |
| If the two numbers differ | Use the ACH number for the ACH payment | Use the wire number for the wire |
| If the form is unclear | Ask which payment network the option uses | Ask the bank to match its fields to the recipient’s wire instructions |
For Bitcoin purchases, our ACH buying guide explains bank authorization and settlement. The wire transfer guide covers the separate wire route. Choose the intended method before copying bank details.
A $1,000 example: choose one payment route
Suppose Alex wants to pay a $1,000 invoice. The biller offers ACH debit and bank wire as alternatives. Alex’s bank displays separate ACH and wire routing fields. Here is what changes between the two choices; the example describes a general bill payment.
Scroll across the table to see all columns.
| Choice | What Alex checks | Before authorizing |
|---|---|---|
| ACH debit through the biller | Alex enters the ACH routing number and separate account number for Alex’s funding account in the biller’s verified payment form. | Review the $1,000 amount, any additional fee, debit date and one-time or recurring authorization. Save the receipt. |
| Wire through Alex’s bank | Alex obtains the biller’s verified receiving wire instructions and enters the recipient’s wire routing and account details. | Check recipient details, payment reference, fee and expected delivery. Confirm when the biller applies the payment. |
Notice whose details changed: the ACH debit form uses Alex’s funding account; the outgoing wire uses the biller’s receiving account. If Alex already authorized the ACH debit and later wants to wire instead, Alex should first ask the biller about the existing payment’s status and cancellation options. Keeping one clear payment record helps avoid paying the invoice twice.
What if you used the wrong routing number?
If you’re still on the review screen, pause and confirm the details through your bank. If you already submitted, contact the bank or service that started the payment promptly. Give it the amount, date, payment method and confirmation reference, then ask whether the payment can still be corrected or canceled.
An incorrect number can cause rejection, delay or return; the outcome depends on the submitted details and processing stage. Check the existing payment before making another attempt. If the details came from an unexpected message or you suspect fraud, contact your bank immediately through a trusted channel.
For an ACH payment already in progress, our ACH trace-number guide explains what to ask the sender for. Keep full account numbers inside the bank or provider’s secure support process.
Before-you-pay checklist
Keep this list beside the form while you review it.
- Identify the payment: ACH debit, ACH credit or wire. Ask the service if its label is unclear.
- Confirm whose account details belong in the form: your funding account or the recipient’s receiving account.
- Open the exact account in the official bank app or obtain current receiving instructions through a trusted channel.
- Match the routing number to the payment method. Check all nine digits and preserve any leading zero.
- Review the separate account number, account type and requested account-holder details.
- Check the amount, complete fee, date and any recurring-debit permission. Follow the service’s account-verification steps.
- Save the confirmation and expected next step. Check an existing payment’s status before retrying.
Common questions about ACH routing numbers
Is an ACH number the same as an account number?
An ACH routing number identifies the financial institution for the payment. The account number identifies the account there. Enter each in its own field. U.S. Bank’s explanation describes the nine-digit routing number used with checking and savings accounts.
Can I use my check’s routing number for direct deposit?
Check your bank’s current direct-deposit or ACH instructions for the account. This is especially useful with an old checkbook or after a bank merger. Use the bank’s direct-deposit form when your employer accepts it.
Does every account at the same bank have the same routing number?
Banks can have multiple routing numbers. Confirm the exact account and payment method rather than copying a number from another person’s account or selecting a state based only on where you live today.
Can I give someone my ACH details?
Share the details through a trusted process for an intended payment, such as your employer’s payroll setup or a biller you chose. Treat them as sensitive banking information. For a debit, read what you are authorizing; never provide your banking password or a one-time sign-in code to someone requesting payment details.
Using bank details for a Bitcoin purchase
Fiat2Bitcoin purchases remain unavailable while provider launch checks are completed. The planned provider-hosted routes include Paybis for ACH and Transak for wires. Fiat2Bitcoin receives neither purchase funds nor crypto and issues no bank instructions. Any future purchase should follow the selected provider’s actual offer and account-verification process.
Use the ACH buying guide or wire buying guide to prepare questions about fees, payment status and wallet delivery. Keep the bank-payment record and the provider’s Bitcoin order reference together so a support team can locate the right transaction.
Sources & further reading
General payment information and purchase-specific details serve different purposes. Review the current offer and terms before proceeding.
- American Bankers Association — Routing number
- Bank of America — Routing number FAQs
- Wells Fargo — Account numbers and routing numbers
- U.S. Bank — ACH routing numbers
Original Fiat2Bitcoin guide. Examples are illustrative; they are not live quotes or customer transactions. How we prepare our guides.