If your bank shows a debit but the Bitcoin provider cannot match the money to your order, start with the existing payment. For the purchase steps around it, see our ACH Bitcoin buying guide. Fiat2Bitcoin's account and payment services remain unavailable during launch preparation; this guide explains how to investigate an ACH-funded purchase with the provider handling it.
What does an ACH trace number identify?
The trace number identifies an ACH entry in the banking system. Kraken's explanation of ACH trace numbers describes the 15-digit reference and its use when investigating missing deposits. Its support process is an example from that provider, not a Fiat2Bitcoin funding arrangement.
A reference is useful because several payments can have the same amount or similar dates. Pair it with the amount, date and company name so the bank and purchase provider can discuss the same entry. Keep all digits as supplied, including any leading zero. Do not change the reference to make it fit an order-number field.
Having a number is not the same as having a final outcome. A payment may need investigation, may have been returned, or may still need to be matched to an order. Ask for its status as well as its identifier.
Where can you find the ACH trace number?
Look in the transaction's detail screen or receipt first. If you see only a general confirmation number, ask whether it is the actual ACH trace number. Banks and providers use their own labels, so a number's appearance alone is not enough to identify it.
Who initiated the ACH matters. If you instructed your bank to send an ACH credit, ask that bank about the outgoing payment. If a purchase provider collected an authorized ACH debit, your bank can investigate the debit on your account, while the provider can ask its payment partner about the collection. Do not assume your bank originated every payment that reduced your balance.
- Open the existing bank transaction and purchase order through their known apps or websites.
- Match the dollar amount, company description and relevant dates; note whether the bank entry is pending or posted.
- Ask the bank or initiating provider for the ACH trace number and the status of that specific entry.
- If the records do not agree, request an investigation and keep the support case reference and next-update date.
Nacha directs consumers to their bank or the organization initiating the payment. Nacha does not hold individual payment records. Searching its website with your trace number will not reveal your transfer.
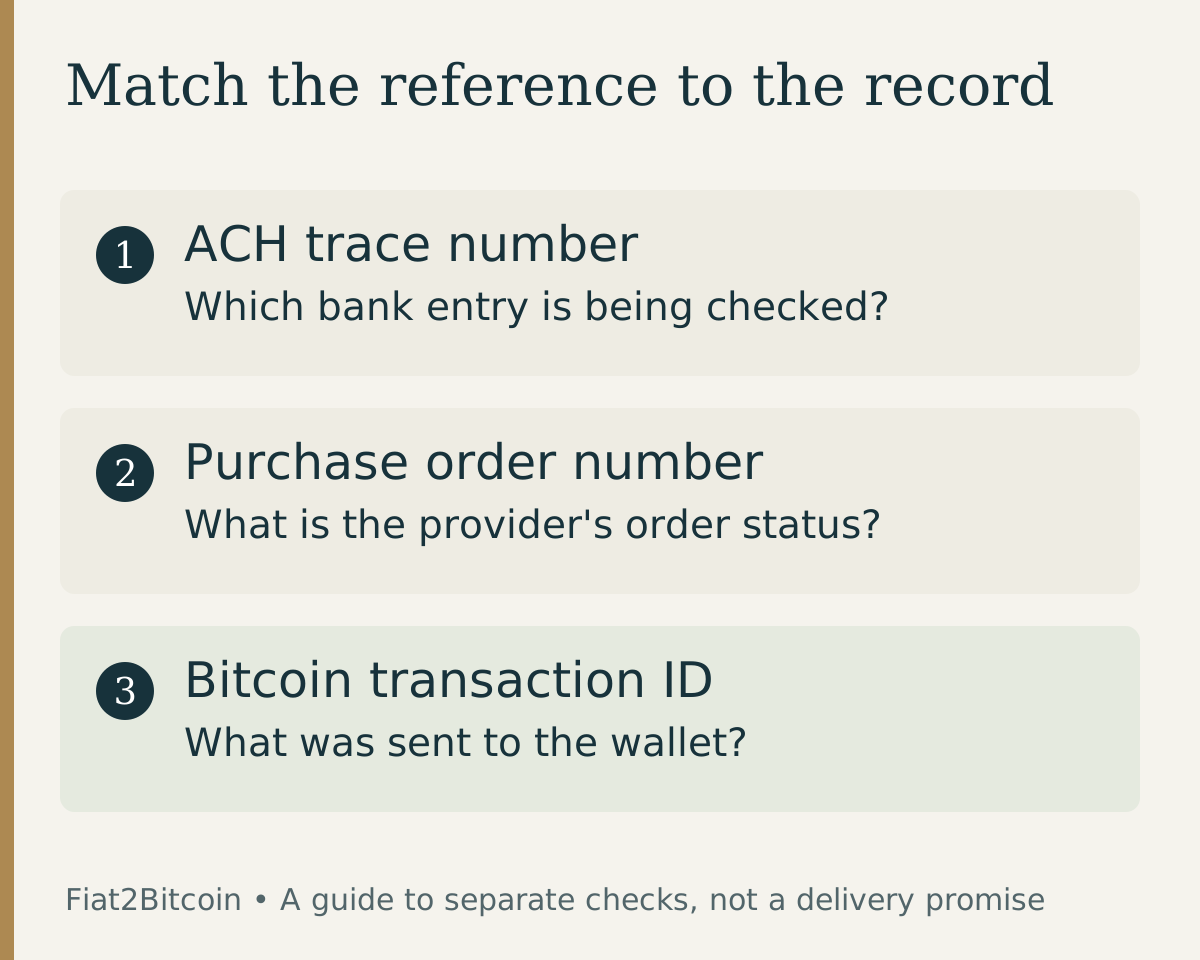
ACH trace number, order number or Bitcoin transaction ID?
Scroll across the table to see all columns.
| Reference | What it identifies | Who can explain it |
|---|---|---|
| ACH trace number | A dollar-payment entry | Your bank and the initiating company or its payment partner |
| Purchase or order number | The provider's purchase record | The provider handling the order |
| Support case number | An investigation or conversation | The team that opened the case |
| Bitcoin transaction ID | An on-chain Bitcoin transaction | The delivery record and the relevant Bitcoin transaction data |
An ACH reference cannot be used as a Bitcoin transaction ID. If the provider has not sent Bitcoin, repeatedly checking a blockchain explorer will not locate the bank payment. If the provider says Bitcoin was sent, ask for the delivery record and confirm the network, destination and amount separately.
What can a bank payment trace tell you?
The Federal Reserve's Payment Trace Request guide describes a bank-to-bank inquiry about whether a payment was received, returned or posted. This is a service for participating financial institutions, not a public tracking portal that a buyer completes directly.
Ask your bank or provider to translate the response into a next step. ‘Posted’ should identify where it posted. ‘Returned’ should come with the reason and the record it relates to. ‘Not found’ should prompt a check of the entry details and dates, rather than an assumption that the money is lost.
If a return code appears, use the ACH return-code guide. If the bank payment is accounted for but Bitcoin is still unavailable, use the ACH settlement and delivery guide to ask about the remaining purchase conditions.
A message you can adapt for support
Send this through the bank's or provider's authenticated support channel. Replace the bracketed fields with your records, and provide sensitive details only through the secure process the institution specifies.
I am checking the ACH payment associated with order [order reference]. The amount is [amount], the bank description is [description], and the bank shows [status] dated [date]. Can you confirm the ACH trace number, whether this entry was posted or returned, and which step remains unresolved? Please provide a case reference and the expected next update.
Keep the bank response with the order record. If there are multiple entries, list them separately instead of combining them into one total. A second debit might be a different attempt and needs its own explanation.
Before you retry or share your records
Do not authorize a replacement payment until the provider explains whether the original can still complete and how a new attempt would be handled. A delay is not evidence that the first authorization has disappeared.
Keep bank statements and payment references out of public posts. Start with the minimum information support needs, and redact unrelated transactions. A legitimate payment investigation does not require your wallet seed phrase or private keys.
If you do not recognize the debit or suspect fraud, contact your bank promptly through its known contact channel. Do not wait for a routine delivery estimate to expire. For an ordinary pending order, the payment-status checklist helps you organize the bank, purchase and delivery evidence.
Sources & further reading
General payment information and purchase-specific details serve different purposes. Review the current offer and terms before proceeding.
- Kraken: What is an ACH trace number?
- Nacha: Consumer FAQs on ACH payments
- Federal Reserve: Payment Trace Request
Original Fiat2Bitcoin guide. Examples are illustrative; they are not live quotes or customer transactions. How we prepare our guides.