A ‘failed’ notification can describe a bank problem, a verification problem or an order decision. Start by finding out which one occurred. Our ACH Bitcoin purchase page explains the planned buying route. Fiat2Bitcoin remains prelaunch, with account and payment services unavailable; the guidance below does not create a refund or retry policy.
First, get the exact return code
Ask the bank or purchase provider for the complete code, the payment amount, the original date and the affected order. An ACH return code usually appears as R followed by two digits. A checkout error or a bank-linking failure may use a different system, so do not guess an ACH code from the word ‘declined.’
Record whether money ever left your available balance, whether a corresponding credit appears, and whether another attempt is pending. Screenshots from different dates can show different stages. Keep the original records together and ask the bank to explain the current balance effect.
ACH return codes to recognize
These are selected codes relevant to bank-funded purchases, not a complete operating manual. The meanings below are paraphrased from Moov's ACH return reference and Nacha's R10/R11 guidance. Your bank and provider must determine what applies to the actual entry.
Scroll across the table to see all columns.
| Code | What it generally means | Ask before another attempt |
|---|---|---|
| R01 | Available funds were too low for the debit | What balance was available when this entry was processed? |
| R09 | The ledger balance included funds that were not yet collected | Which funds were unavailable, and when can the bank confirm availability? |
| R02 | The account has been closed | Which saved account did the provider use? |
| R03 | The account could not be located or matched to the receiver | Do the submitted account details match the intended open account? |
| R04 | The account-number format is invalid | Was the correct account number entered in the correct field? |
| R10 | The customer reports an unknown originator or an unauthorized debit | What payment is being reported, and what records does the bank need? |
| R11 | A debit did not follow the terms of an existing authorization | How did the amount, date or other payment terms differ from the authorization? |
R03 versus R04: check the account details
R03 and R04 describe different account-detail problems. R03 can involve a number that passes format checks but does not identify the intended receiver's open account. R04 concerns an invalid account-number structure. Neither code is a request to send Bitcoin or pay a fee to an unfamiliar person to ‘unlock’ the account.
Compare the information in the provider's secure account screen with your bank's own instructions for ACH. Check the account type and which saved account was selected. Use the bank's app, website or established contact channel for corrections; do not copy bank details from a search snippet or another customer's instructions.
If the bank connection itself is incomplete, resolve that first. The micro-deposit verification guide explains one possible validation method. Correcting a saved account does not automatically fix or cancel the original payment entry; ask the provider what happens to that order.
R01 versus R09: ask about available funds
A balance displayed now does not explain what was available when a debit was processed. Ask the bank about the affected entry and the balance at that time. For R09, ask specifically about funds still awaiting collection. Avoid moving money based only on an assumed retry date.
Before adding a new purchase, ask whether the provider intends another collection attempt under the existing authorization. Confirm the amount, timing and any disclosed charges. A fresh order could create an additional obligation while the earlier one is still being resolved.
Does an ACH return cancel or refund the Bitcoin purchase?
The return code alone cannot answer that. Confirm the bank payment's outcome and the provider's order outcome separately. Ask whether the order is open, canceled, awaiting another payment, or already delivered, and request the applicable terms rather than assuming a universal policy.
If the provider says money is being returned to you, ask for the amount, payment method, reference and expected timeframe. Then verify the corresponding bank entry. A notification that a debit failed is not proof that a separate refund has posted.
If Bitcoin was already delivered, a bank return does not itself undo that transaction. Do not assume that a returned debit eliminates any obligation under the purchase terms. Ask the provider for an itemized explanation of the order and follow its established dispute process if the records do not agree.
Resolve the original entry before retrying
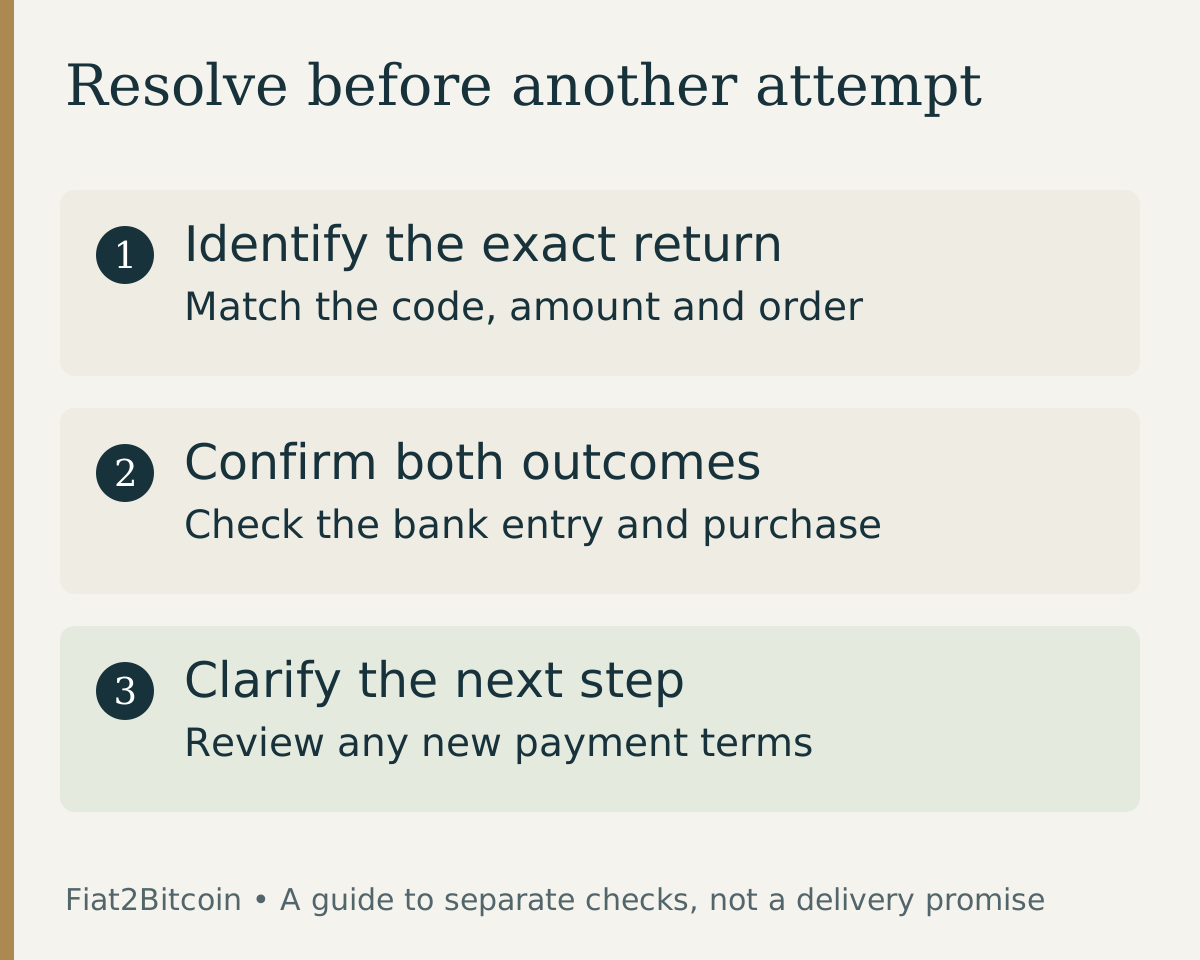
- Save the exact code, amount, date, bank description and original order number.
- Ask which record is final and whether another debit is pending or planned.
- Correct only the issue confirmed by the bank or provider through its secure process.
- Confirm any new authorization, quote, charges and delivery conditions before accepting a replacement purchase.
- Keep the case open until the bank entry and purchase outcome are both explained.
If support cannot find the bank entry, the ACH trace-number guide shows what reference to request. If the payment has not been returned but delivery is delayed, use the ACH timing guide instead of treating every delay as a failed payment.
Sources & further reading
General payment information and purchase-specific details serve different purposes. Review the current offer and terms before proceeding.
- Moov ACH: Return-code reference
- Nacha: Differentiating unauthorized return reasons
- Nacha: Consumer FAQs on ACH payments
Original Fiat2Bitcoin guide. Examples are illustrative; they are not live quotes or customer transactions. How we prepare our guides.