Which action are you actually considering?
“Gold IRA” and “Bitcoin IRA” commonly describe investments or services, not enough information to establish the account’s legal type. Ask whether the existing account is traditional, Roth or another arrangement, and whether the proposed receiving account has the same owner and tax character.
IRS Publication 590-A distinguishes direct trustee-to-trustee transfers of traditional IRA funds from rollovers involving a distribution, and separately addresses traditional-to-Roth conversions. A properly structured direct transfer is not the same thing as receiving funds personally and later sending money somewhere else. The source does not make every transaction using the word “transfer” valid or tax-free.
Scroll across the table to see all columns.
| Action being discussed | What may change | What must be verified |
|---|---|---|
| Change investments within the IRA | Gold exposure, cash and BTC exposure | Custodian support, investment permissions and trade execution |
| Move to another IRA custodian | The administering trustee/custodian and possibly custody arrangements | Owner, legal account type, accepted assets and transfer instructions |
| Traditional-to-Roth conversion | The account’s tax character | Separate conversion rules and potential income inclusion |
| Distribution to a personal account | Funds leave the IRA framework unless a valid rule applies | Consequences, deadlines and eligibility before any movement |
What must the two custodians agree to accept?
Ask the current custodian how the gold is held, how a sale would be executed and what the actual liquidation bid would be. Ask the receiving custodian which IRA assets and BTC exposure it supports, who holds the crypto and what fees and restrictions apply. Some plans may require a coordinated sale and cash transfer rather than an in-kind movement; do not assume every custodian accepts physical metal or direct BTC.
The SEC’s self-directed IRA alert explains that custodial administration is different from validating an investment or its performance. The CFTC also warns about sales pitches presenting virtual-currency IRAs as “IRS approved.” Permission for an entity to act as a custodian is not approval of a particular investment, return or promotional claim.
Use the IRS IRA investment FAQs for the general rules and restrictions, including prohibited-transaction concerns. This guide does not evaluate your custodian, metal holding, account eligibility or proposed transaction. A qualified adviser and the actual custodians need the relevant facts before you act.
A fictional valuation-to-purchase cash bridge
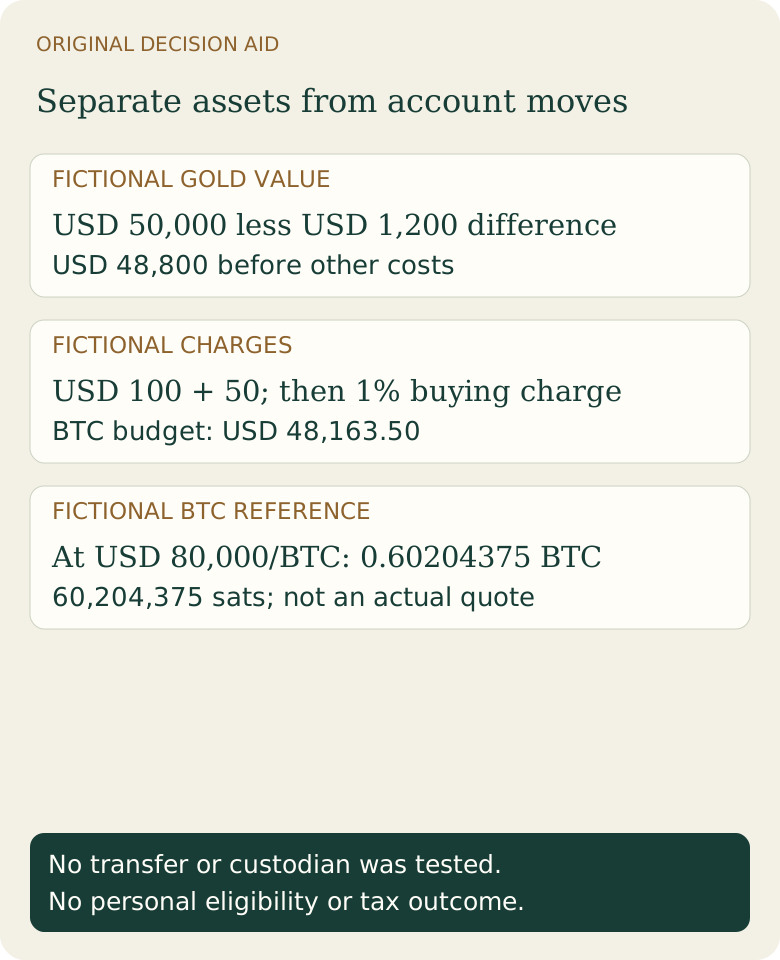
Start with a hypothetical USD 50,000 reported gold holding value. Invent a USD 1,200 difference between that value and a confirmed sale amount, producing USD 48,800. Subtract invented USD 100 exit/administration and USD 50 transfer charges: USD 48,650 remains before buying BTC.
Assume, solely for this model, a 1% buying charge taken from that remaining cash: USD 486.50. BTC purchase value becomes USD 48,163.50. At a fictional USD 80,000/BTC quote, it buys 0.60204375 BTC, or 60,204,375 satoshis. None of these numbers is a custodian quote, a gold appraisal, a current BTC price or a Fiat2Bitcoin fee.
Scroll across the table to see all columns.
| Step | Illustrative amount | Meaning |
|---|---|---|
| Reported starting value | USD 50,000.00 | Not guaranteed liquidation proceeds |
| After invented sale-value difference | USD 48,800.00 | Subtract USD 1,200 |
| After exit/admin and transfer charges | USD 48,650.00 | Subtract USD 100 and USD 50 |
| Invented purchase charge | USD 486.50 | 1% of USD 48,650 |
| BTC purchase value | USD 48,163.50 | Cash after the modeled charge |
| BTC quantity at stated invented quote | 0.60204375 BTC | 60,204,375 sats at USD 80,000/BTC |
What evidence shows each stage is complete?
Retain the actual sale confirmation, custodian transfer reference, receiving-account credit and BTC trade confirmation as separate records. An instruction submitted is not proof of a completed sale, accepted transfer or settled BTC purchase. Compare the resulting custody arrangement with what you approved.
Read the fee schedule for liquidation spreads, account closing, transfer, purchase, administration, custody and eventual withdrawal. Verify which charges are already included in the quote so they are not counted twice. The ETF-versus-direct-BTC guide addresses a separate question: the type of exposure, not the correct way to move an IRA.
What this guide does not authorize or determine
A traditional-to-Roth conversion may involve income inclusion under IRS rules; changing from gold to BTC is not, by itself, a Roth conversion. The right treatment depends on the facts. This article does not calculate tax, determine rollover eligibility, interpret your plan documents or recommend a retirement allocation.
Download the original IRA movement worksheet for the action map and fictional cost bridge. Fiat2Bitcoin is not an IRA custodian, retirement-account administrator or tax adviser. Its consumer Bitcoin purchase methods must not be assumed to provide an IRA trading or transfer facility. Consult the actual custodians before moving retirement assets.
Sources & further reading
These sources explain the payment systems and rules discussed in this guide. For your purchase, check the provider’s current offer and terms.
- IRS Publication 590-A: trustee transfers, rollovers and Roth conversions
- SEC Investor.gov: self-directed IRA custody and fraud risks
- CFTC: claims of IRS-approved virtual-currency IRAs
- IRS: IRA investment and prohibited-transaction questions
Original account/asset distinction and fictional cost-bridge arithmetic. No IRA was opened, assets moved, gold sold, BTC bought, custodian approved or personal tax outcome determined. How we prepare our guides.