Why can buying Bitcoin count as a cash advance?
A cash advance can cover more than taking cash out of an ATM. Some issuers treat cash-equivalent transactions differently from ordinary shopping. The CFPB specifically identifies cryptocurrency purchases as a type of transaction that could trigger a cash-advance fee.
That does not mean every card classifies every crypto purchase the same way. Your agreement, issuer and transaction details matter. Ask the issuer about the particular purchase rather than relying on another person's statement or an old list of ‘crypto-friendly’ cards.
Provider acceptance and issuer pricing are separate. A checkout can display a credit-card option without establishing that your issuer will authorize the payment or treat it as a normal purchase. The credit-card purchase guide puts those checks in order.
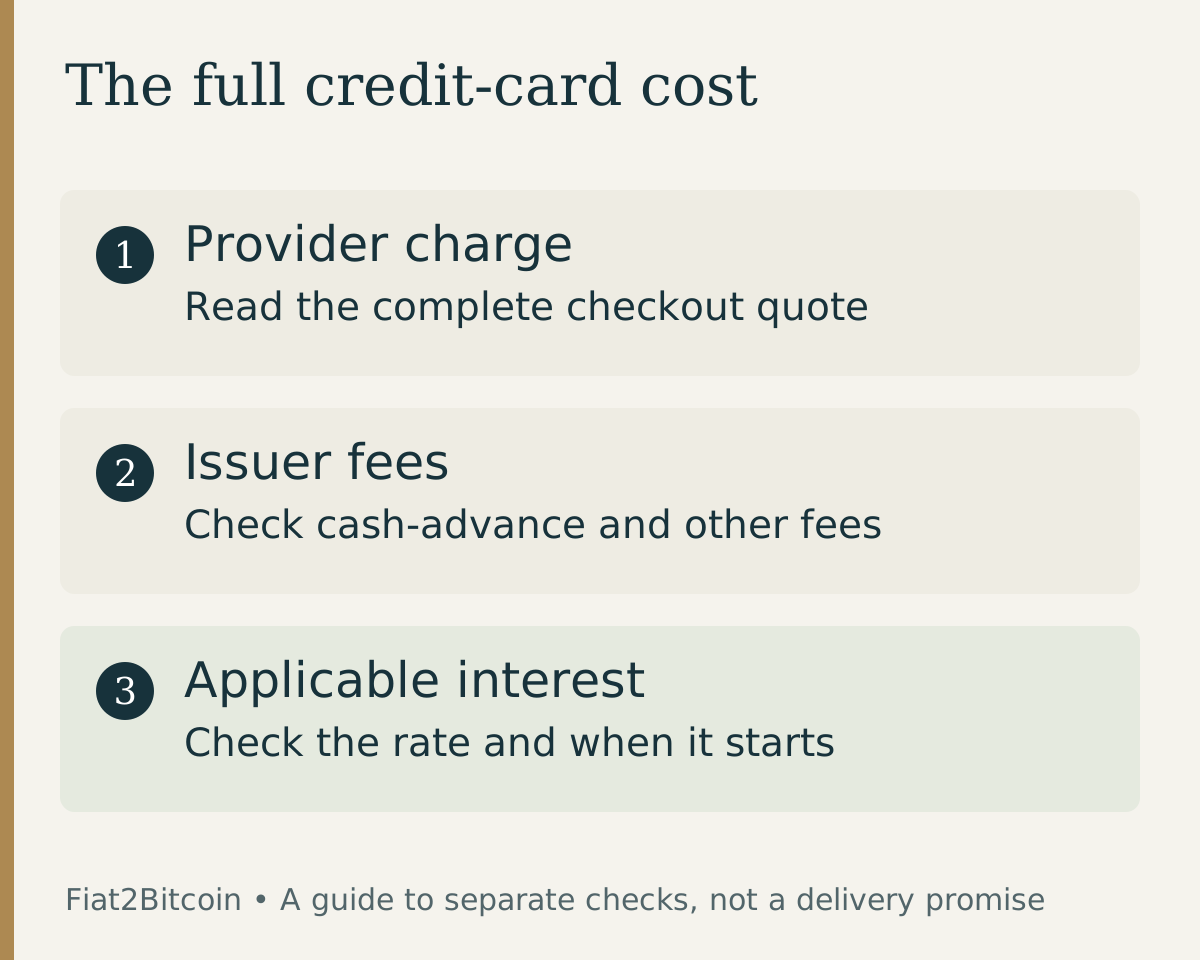
Check four possible cost layers
Scroll across the table to see all columns.
| Cost or condition | Where to check | Question to ask |
|---|---|---|
| Purchase quote | The selected provider's checkout | What is the total charge and quoted Bitcoin delivery amount? |
| Cash-advance fee | The card agreement and issuer | Is there a percentage fee, a minimum fee, or both? |
| Interest | The cash-advance APR and balance terms | When does it start and how is the interest-bearing balance calculated? |
| Other card terms | The issuer | Do currency charges, separate limits or rewards exclusions apply? |
The CFPB explains that cash advances commonly carry a higher rate and begin accruing interest immediately. The agency also notes that a cash-advance limit may be lower than the overall credit limit. Confirm your own terms rather than assuming your available credit is the amount you can use.
A simple cost example
The following numbers are invented to demonstrate the arithmetic. They are not a Fiat2Bitcoin quote, a quoted card APR or a prediction of your statement. Suppose a provider charges $500, the issuer adds a 5% fee, and a hypothetical 30% annual rate accrues on a $500 principal for 30 days using a 365-day year.
Scroll across the table to see all columns.
| Item | Calculation | Illustrative amount |
|---|---|---|
| Provider charge | Assumed checkout total | $500.00 |
| Issuer cash-advance fee | $500 × 5% | $25.00 |
| Simple interest illustration | $500 × 30% × 30 ÷ 365 | $12.33 |
| Total outlay in this illustration | $500 + $25 + $12.33 | $537.33 |
Actual interest can differ because of daily balances, compounding, fees included in the interest-bearing balance, payment allocation and the issuer's calculation method. Any additional foreign-transaction charge is excluded here. The quoted Bitcoin amount is also unknown, so this example cannot establish an effective Bitcoin exchange rate.
A useful comparison records the quoted Bitcoin alongside the complete dollar outlay. Our purchase-cost guide explains that calculation. Compare offers at similar times and within their expiry windows; a fee percentage alone is not the full price.
What to ask your issuer before checkout
Use the issuer's official contact route, such as the number on your card or the secure banking app. Describe the cryptocurrency purchase and the provider. Keep the relevant agreement or response with your purchase records.
- Is this cryptocurrency purchase permitted on my card?
- Would it be classified as a purchase or a cash advance?
- What fee and minimum fee would apply?
- Which APR applies, and when does interest start?
- Is there a separate cash-advance limit or restriction?
- Would any currency fee apply, and does the transaction qualify for rewards?
- How would a payment be allocated if I already carry other balances?
Questions about interest, rewards and repayment
Does paying before the statement arrives avoid all interest?
Do not assume so. Chase explains that cash advances generally lack a grace period. Ask your issuer how much is due, whether interest has already accrued and how payment allocation works for your balance.
Can rewards offset the fee?
Count rewards only if the issuer confirms the transaction is eligible, and evaluate them against all charges. A reward estimate does not cancel a cash-advance fee, borrowing cost or possible loss on Bitcoin.
What if the Bitcoin price falls after the purchase?
The card debt and its repayment terms remain separate from Bitcoin's market value. Do not rely on a future price increase to make the borrowing affordable. This guide explains payment costs; it does not recommend financing an investment with debt.
Compare the method before authorizing payment
Use the credit-card Bitcoin purchase guide to review eligibility and the quote. If borrowing is not appropriate, compare an eligible debit-card route or ACH route, including their own costs and timing. Resolve any pending attempt before switching methods.
Fiat2Bitcoin remains prelaunch, with registration and payments unavailable. Its approved wire-fee schedule does not apply to card purchases. Future card offers will depend on Changelly and the selected provider, and your issuer's separate terms will still matter.
Sources & further reading
General payment information and purchase-specific details serve different purposes. Review the current offer and terms before proceeding.
- CFPB: Cash-equivalent transactions and cash-advance charges
- CFPB: Cash-advance limits, fees and interest
- Chase: Cash-advance costs and how they work
Original Fiat2Bitcoin guide. Examples are illustrative; they are not live quotes or customer transactions. How we prepare our guides.