A bank app can show two different balances for the same account. The larger number is not automatically money you can use, and the smaller number is not a complete spending plan. This guide concerns deposit accounts; a credit card’s current balance and available credit describe borrowing instead.
For an ACH Bitcoin purchase or debit-card purchase, available bank funds are only one check. Fiat2Bitcoin purchases remain unavailable during launch preparation. A balance display does not establish an eligible offer, payment approval or Bitcoin delivery.
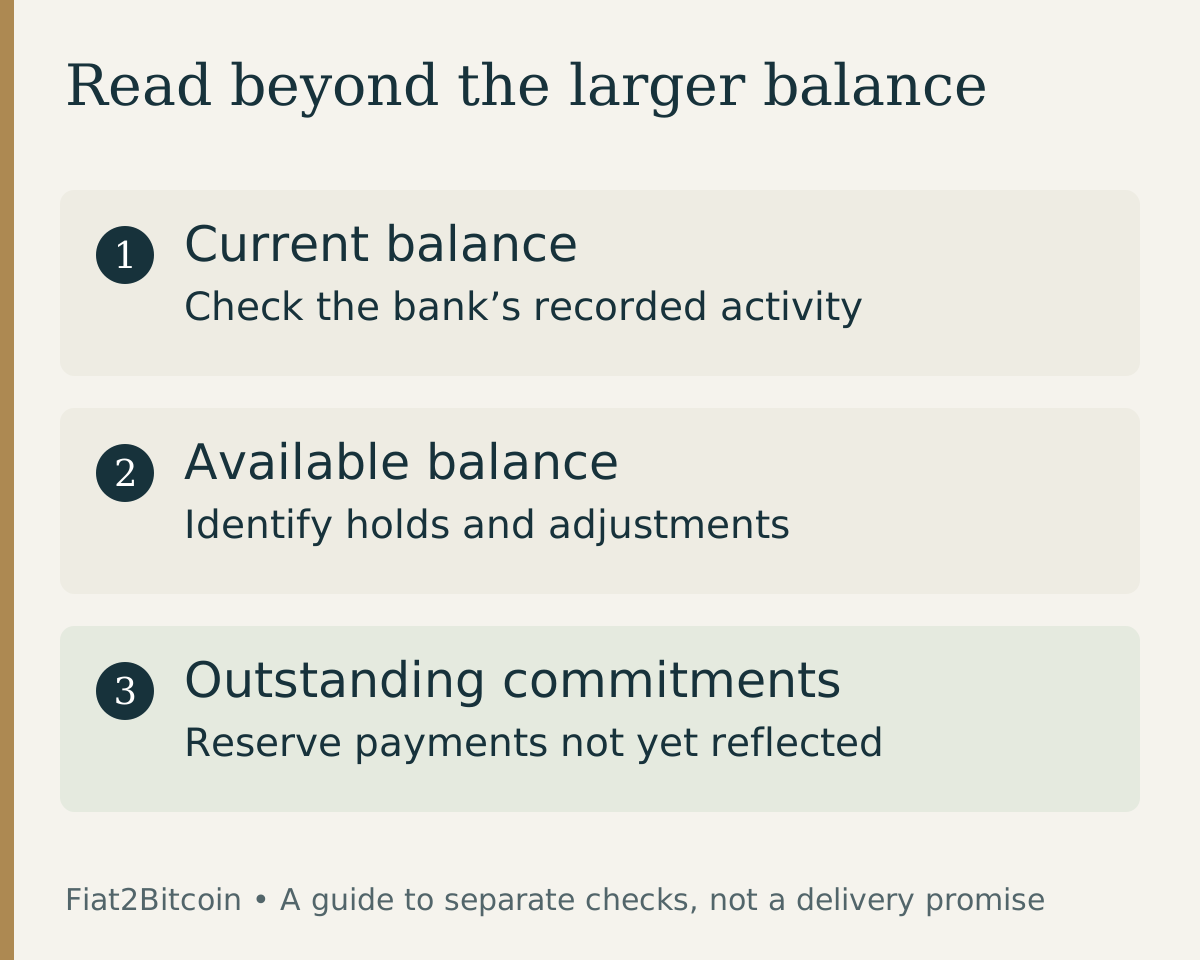
What do current balance and available balance mean?
Banks use labels such as current, account, ledger or present balance for their account records. The precise calculation can differ. Read the explanation for your own account rather than assume every app uses the same definition.
North Shore Bank’s balance explanation distinguishes its current balance from the amount available at a particular time. It identifies deposit holds and card authorizations as reasons the available amount may be lower.
Scroll across the table to see all columns.
| Display | What to ask | What it does not prove |
|---|---|---|
| Current or ledger balance | Which deposits and withdrawals are included in this record? | That every dollar is available for a new payment |
| Available balance | Which funds does the bank make available now, and which adjustments are included? | That all scheduled or outstanding payments have been deducted |
| Your payment plan | What obligations have I authorized that the bank has not reflected yet? | That a bank or purchase provider will approve another transaction |
Why is available balance lower than current balance?
A deposit can appear in an account record while some funds remain unavailable. A card authorization can also reduce the amount the bank makes available before the final charge is recorded. Your bank can explain which entries account for the difference.
The CFPB’s mobile-banking guidance notes that a pending card amount can differ from the eventual posted amount. It also advises checking the bank’s funds-availability policy before relying on a pending deposit.
If a label refers specifically to an ACH hold, use the ACH-hold guide to identify the restriction. A different balance alone does not identify a hold’s cause, release date or effect on an existing order.
A simple balance example
Suppose a fictional account shows a $1,000 current balance. Its bank has included a deposit in that figure but still holds $300 of it. A separate $200 card authorization also reduces availability. Assume these are the only bank adjustments in this example.
Scroll across the table to see all columns.
| Step | Amount | Meaning in this example |
|---|---|---|
| Current balance | $1,000 | The bank’s starting account record |
| Unavailable part of a deposit | −$300 | Included in the record, unavailable for withdrawal |
| Pending card authorization | −$200 | A separate adjustment already reflected by the bank |
| Displayed available balance | $500 | $1,000 minus $300 minus $200 |
| Scheduled payment not yet reflected | −$100 | Reserve separately; do not subtract it twice if the bank later includes it |
| Planning remainder | $400 | Before any other obligations, charges or adjustments |
This is an illustration, not a universal bank formula, a recommendation to spend $400 or a live Bitcoin quote. Ask which adjustments your bank has already included. Account terms and overdraft arrangements can change what a display represents.
Can an available balance miss a payment?
Yes. North Shore Bank explains that some authorized withdrawals, outstanding checks and scheduled payments may not yet appear in its available figure. It also notes that release of a card hold does not necessarily end the obligation if the merchant later submits the charge.
Keep your own list of commitments and compare it with the bank’s entries. Do not count the same authorization twice, but do not assume a missing label means a purchase was canceled. If an earlier Bitcoin order is unresolved, check that order before authorizing a replacement.
What should you check before an ACH or debit payment?
- Check that you selected the intended account, rather than relying only on its nickname.
- Review the bank’s balance definition, pending transactions and any unavailable deposit amounts.
- Reserve for payments you have authorized that are not yet included in the display.
- Read the complete purchase amount and separately disclosed costs; available funds do not determine the Bitcoin price.
- Confirm account eligibility and the applicable bank or card limit, then resolve any existing pending attempt before trying again.
A card’s remaining daily allowance is another limit, separate from the account balance. The debit-card spending-limit guide explains what to ask your issuer. For ACH, review the payment authorization rather than assume linking an account authorizes every payment.
Does a lower balance mean the Bitcoin purchase is complete?
No. The balance is a bank-account observation. The provider’s order status and the Bitcoin delivery record answer different questions. Match the bank amount and date to the existing order reference, then ask which stage remains.
If the provider reports an ACH return, request the exact code and use the return-code guide. If the payment is still processing, the ACH settlement and delivery guide explains the separate milestones. Do not infer a refund, cancellation or completed delivery from a balance change alone.
What should you ask if the numbers do not agree?
Ask the bank which entries explain the difference, whether a deposit is available, which scheduled payments it has received, and whether the amount shown includes an overdraft facility. Ask when the record will next change and what event must occur first.
Ask the purchase provider separately about the existing order, any further collection attempt and the next required step. Keep the answers with the original payment reference. Your bank can explain its display; it cannot establish another company’s Bitcoin delivery from that display alone.
Sources & further reading
General payment information and purchase-specific details serve different purposes. Review the current offer and terms before proceeding.
- North Shore Bank: Current and available balance definitions
- CFPB: Pending transactions and funds availability in mobile banking
Original Fiat2Bitcoin guide. Examples are illustrative; they are not live quotes or customer transactions. How we prepare our guides.