Start with the wire-transfer Bitcoin purchase guide for the planned purchase flow. Fiat2Bitcoin remains prelaunch. This article explains bank terminology; it does not establish international-wire eligibility or provide receiving-account instructions.
What is the difference between ABA and SWIFT?
Scroll across the table to see all columns.
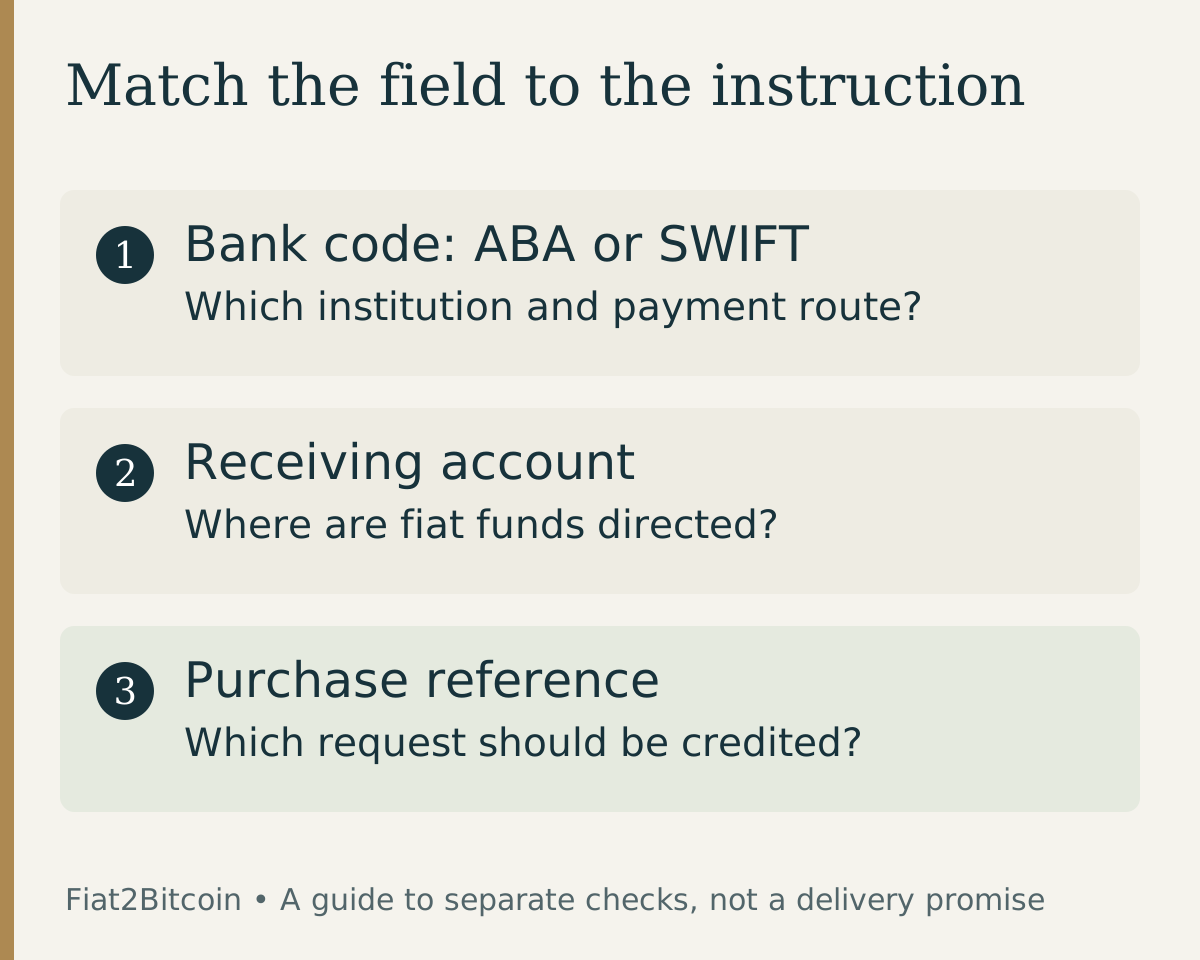
| Detail | Format or purpose | Typical use |
|---|---|---|
| ABA routing number | Nine digits identifying a U.S. financial institution | U.S. payment routing; confirm the number for the required payment type |
| SWIFT / BIC | Eight characters, or eleven with a branch identifier | Identifying a business party such as a bank in financial messaging |
| Account number / IBAN | Identifies the receiving account under the relevant system | Directing the payment to the instructed account |
| Purchase reference | Identifies the request or order | Helping allocate the payment to the correct purchase |
The American Bankers Association maintains information about ABA routing numbers and their ACH and wire attributes. SWIFT's BIC explanation defines the eight-character identifier and optional three-character branch element. A valid-looking code does not establish that it is the right code for your payment.
Neither a routing number nor a BIC is your Bitcoin receiving address. Bank information directs the fiat payment; the cryptocurrency destination is a separate part of the purchase.
Does a domestic wire need ABA and an international wire need SWIFT?
That is a useful starting distinction, but the actual instructions control. For example, Bank of America's wire guide asks for an ABA routing number for its domestic sending flow and a SWIFT code for its international flow, alongside account and recipient details. It also explains that some destinations require additional local identifiers.
An international route can involve more than one bank and more than one identifier. If your instructions include an intermediary bank, keep its details separate from those of the beneficiary's bank. Do not replace the final receiving bank with an intermediary just because its code fits a form field.
Check the sending bank, receiving country, currency and approved purchase route before deciding which fields apply. An educational article about international banking is not confirmation that a Bitcoin provider accepts international wires or a particular currency.
Is an ACH routing number always the same as a wire routing number?
No. Do not assume that the number used for direct deposit or a previous ACH payment is the correct number for a wire. Wells Fargo's account help states that routing numbers differ across account products and wire transfers. Other institutions have their own instructions.
For a Bitcoin purchase, follow the chosen method's exact payment flow. The ACH purchase page explains that separate route, and the ACH-versus-wire comparison explains why switching rails changes the process. Do not convert an ACH instruction into a wire by selecting a different transfer option.
If your bank's form rejects a supplied code, ask the bank what kind of identifier the field expects and ask the purchase provider to verify the instructions. Adding digits, substituting a search result or trying another bank code can direct the payment incorrectly.
Check the whole instruction set before sending
- Confirm that the provider has approved the payment route for this specific request, including the currency and sending account requirements.
- Read the recipient name, bank name, bank code and account details as separate fields. Verify any intermediary or further-credit information.
- Match each field in the sending bank's form to the verified instructions. Ask about missing or ambiguous fields before submitting.
- Confirm any purchase reference exactly as requested and review the complete transfer summary.
- Keep the bank confirmation and purchase reference. Track the fiat payment and Bitcoin delivery as separate outcomes.
For example, imagine verified instructions list a receiving bank plus an intermediary, while your bank's form initially shows only one bank-code box. The correct action is to ask how the bank accepts those instructions. It is not to choose whichever code is easier to paste. This is a hypothetical form-matching example, not a set of usable payment details.
A for-further-credit instruction may serve a separate allocation purpose. Do not place a purchase reference or further-credit name in the bank-code field. Use the wire-instruction verification checklist when confirming the complete request.
Can an online code lookup confirm the payment is safe?
A directory can help check which institution a code identifies. It cannot establish that an account belongs to the intended recipient or that a payment request is genuine. The ABA links to its official routing-number lookup, but a matching bank name is only one piece of the instruction check.
For Fiat2Bitcoin's planned manual wire flow, employees provide request-specific instructions after review. Instructions may differ between requests. Reusing details from an earlier purchase or another customer would bypass that verification.
If you already sent a wire with a possibly incorrect field, contact the sending bank promptly and give it the transfer reference. Notify the purchase provider through its verified channel. Do not send a second wire while the first is unresolved, and do not assume the bank can reverse it. The wire tracking guide explains which records to collect.
Sources & further reading
General payment information and purchase-specific details serve different purposes. Review the current offer and terms before proceeding.
- American Bankers Association: Routing numbers and official lookup
- SWIFT: Business Identifier Code structure
- Bank of America: Domestic and international wire fields
- Wells Fargo: Routing-number differences
Original Fiat2Bitcoin guide. Examples are illustrative; they are not live quotes or customer transactions. How we prepare our guides.